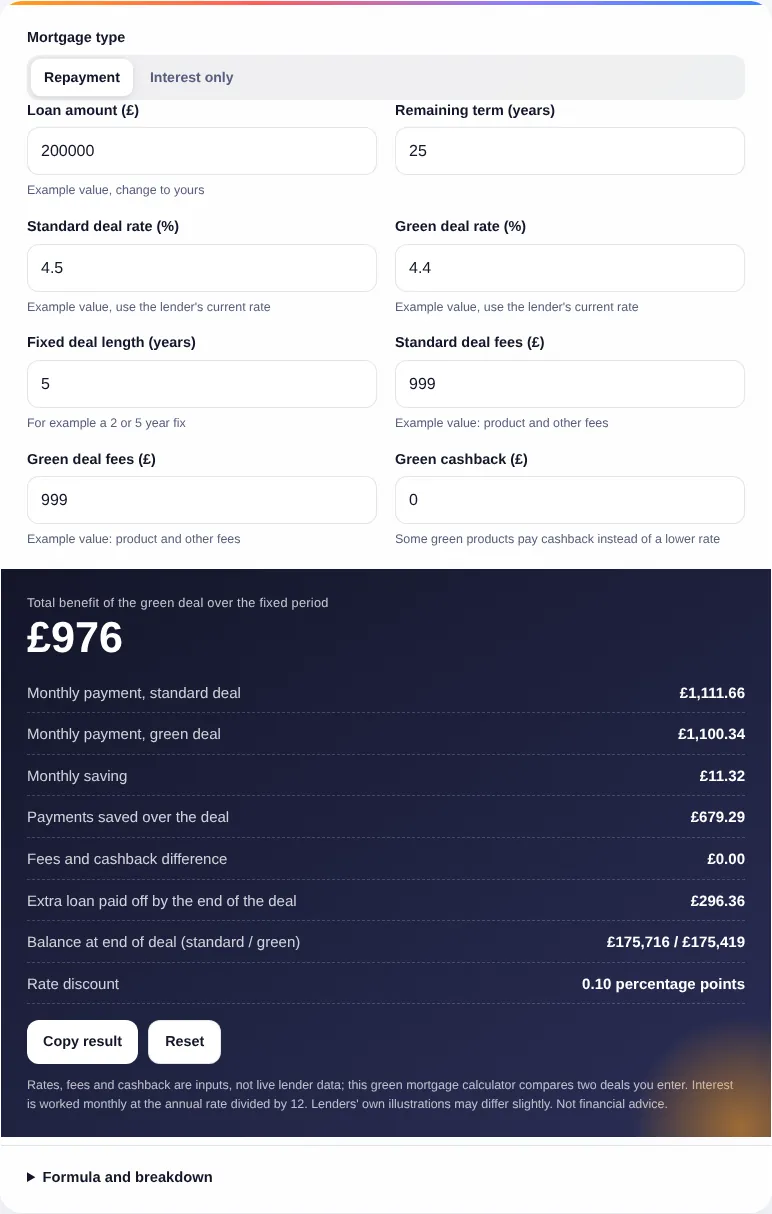
Rates, fees and cashback are inputs, not live lender data; this green mortgage calculator compares two deals you enter. Interest is worked monthly at the annual rate divided by 12. Lenders’ own illustrations may differ slightly. Not financial advice.
Formula and breakdown
n/a
n/a
n/a
This green mortgage calculator compares a green mortgage deal with a standard deal over the fixed period, for UK buyers and homeowners remortgaging a home with a good Energy Performance Certificate. It counts the lower monthly payment, the difference in fees, any cashback and the extra loan the lower rate pays off, so you see the real benefit in pounds rather than a rate gap.
Quick answer: A green mortgage calculator works out the monthly payment at the green and standard rates, multiplies the saving by the months in the fix, then adds the fee difference, cashback and extra loan repaid. On £200,000 over 25 years, 4.40% instead of 4.50% saves £11.32 a month and about £976 over five years.
What Is a Green Mortgage Calculator?
A green mortgage calculator is a tool that measures how much a mortgage linked to an energy efficient home saves compared with an ordinary deal over the same fixed period. In plain words: the benefit equals the monthly payment difference times the number of months in the fix, plus the standard deal's fees minus the green deal's fees, plus any green cashback, plus the difference between the two loan balances at the end of the fix.
The monthly payment uses the standard repayment formula set out in the Wikipedia article on mortgage calculators: payment equals r times P divided by 1 minus (1 + r) to the power minus n, where P is the loan, r the annual rate divided by 12 and n the number of monthly payments left. For interest only, the payment is the loan times the monthly rate.
How Do You Use the Green Mortgage Calculator?
- Choose repayment or interest only.
- Enter the loan amount and the years left on the mortgage.
- Enter the standard deal rate and the green deal rate from the lender's current product list. The figures shown are examples only.
- Enter the length of the fixed deal, for example 2 or 5 years.
- Enter the fees on each deal and any cashback the green product pays.
- Read the total benefit, then check the monthly figures, fee line and end-of-deal balances. A result below zero means the standard deal is cheaper.
What Is a Green Mortgage?
A green mortgage is a home loan that gives a better deal, usually a lower rate or cashback, when the property has a high energy efficiency rating, most often an EPC of A or B. NatWest is a clear example: its green mortgage page says the product is for people buying or remortgaging a home with a valid EPC of A or B, and that it offers a reduced rate on a 2 or 5 year fixed rate deal, with a maximum loan to value of 85% for residential lending. It also notes that product fees and early repayment charges may apply.
Other lenders package the reward differently, for example as cashback on completion. The calculator handles both: enter a lower rate, a cashback amount, or both. Because products change often, always use the lender's current figures.
How Much Does a Small Rate Discount Save?
Each 0.10 percentage point off the rate saves roughly £11 a month on a £200,000, 25-year repayment loan at around 4.5%. The table shows the monthly payment, the saving over a five-year fix and the extra loan repaid, using the same tool for a £200,000 loan over 25 years against a 4.50% standard rate, with equal fees and no cashback.
| Green rate | Discount | Monthly payment | Monthly saving | Benefit over a 5-year fix |
|---|---|---|---|---|
| 4.50% | 0.00 | £1,111.66 | £0.00 | £0 |
| 4.45% | 0.05 | £1,106.00 | £5.67 | £488 |
| 4.40% | 0.10 | £1,100.34 | £11.32 | £976 |
| 4.30% | 0.20 | £1,089.08 | £22.58 | £1,950 |
| 4.20% | 0.30 | £1,077.88 | £33.78 | £2,923 |
The benefit column includes both the payments saved and the slightly lower balance at the end of the fix. Notice how small the monthly figures are next to typical product fees. That is why the fee lines in the green mortgage calculator matter as much as the rate.
Can Fees or Cashback Change the Answer?
Yes, a fee difference can wipe out a small discount, and cashback can be worth more than a rate cut on a short fix. Example: on £250,000 over 30 years, a two-year fix at 4.05% instead of 4.20% saves £21.79 a month, £522.89 over 24 months, and leaves £223.54 less owed. If the green deal's fee is £500 higher, the total benefit falls to about £246.
Compare that with a green product at the same 4.20% rate that pays £500 cashback: the benefit is exactly £500, roughly double. Run both versions in the green mortgage calculator before choosing, and include valuation or legal fees if they differ between the deals.
How Do You Check Whether a Home Qualifies?
Look up the home's EPC rating, which runs from A, the most efficient, to G, the least. GOV.UK says an EPC is valid for 10 years, and you can find and download any existing certificate free through the find an energy certificate service. If the rating is C or D, the EPC rating estimate and the EPC improvement cost estimate show what an upgrade could involve.
Energy savings from an efficient home sit on top of any mortgage benefit. Measures such as solar panels can lower bills; the solar savings calculator and the solar payback calculator estimate those separately, and the heat pump running cost calculator compares heating costs.
Worked Example: Rate Discount Against a Higher Fee
Example: a household remortgages £250,000 with 30 years left. The standard two-year fix is 4.20% with a £999 fee. The green two-year fix is 4.05% with a £1,499 fee and no cashback.
- Standard payment: £1,222.54 a month. Green payment: £1,200.76 a month.
- Payments saved: £21.79 x 24 months = £522.89.
- Fee difference: £999 minus £1,499 = minus £500.
- Balance after 24 months: £241,314.47 standard, £241,090.93 green, so £223.54 less owed.
- Total benefit: £522.89 minus £500 + £223.54 = £246.43.
The green deal still wins, but by far less than the monthly figure suggests. With the same fee on both deals, the green mortgage calculator shows £746.43 instead.
Frequently Asked Questions
What is a green mortgage?
It is a mortgage that rewards an energy efficient home, usually one with an EPC rating of A or B, with a lower rate, cashback or a cheaper further advance for improvements. NatWest, for example, offers a reduced rate on 2 or 5 year fixes for homes rated A or B.
How much can a green mortgage save?
It depends on the size of the discount, the loan and the deal length. On £200,000 over 25 years, a rate of 4.40% instead of 4.50% saves £11.32 a month and about £976 over a five-year fix, including the extra loan repaid. Fees can cancel that out.
Is a green mortgage always cheaper?
No. A green deal with a slightly lower rate but a higher product fee can cost more over the fixed period than a standard deal. Enter both deals with their fees and any cashback in the calculator; a negative result means the standard deal is cheaper.
What EPC rating do I need for a green mortgage?
Most green products ask for an EPC rating of A or B; NatWest, for example, requires a valid EPC of A or B. An EPC is valid for 10 years, and you can check a home's rating free with the GOV.UK find an energy certificate service.
Why does the calculator include the balance at the end of the deal?
On a repayment mortgage, a lower rate means less of each payment goes on interest, so more goes to paying off the loan. At the end of the fix you owe slightly less, which is a real benefit that a monthly payment comparison alone misses.
Can I get a green mortgage on an older home?
Yes, if the home has a qualifying EPC rating, whatever its age. If it does not, improvements such as insulation or a heat pump could lift the rating. Check what an upgrade would cost and which band it could reach before you apply, and remember any new EPC must reflect the work.
Checked October 2026 by the Solaxyra Editorial Team. Sources: NatWest: Green Mortgages, GOV.UK: Energy Performance Certificates, GOV.UK: Find an energy certificate, Wikipedia: Mortgage calculator.